U.S. Small Business Administration · 7(a) / 504 FOIA
SBA Loans by Industry and State
Explore the SBA loan amounts approved for five industries, by state, program and fiscal year.
FY2020–2025 approvals · as of June 30, 2026 · cancelled loans excluded
Explore every state ↓FY2025 · 7(a) · Restaurants and other eating places · 7225 · as of June 30, 2026
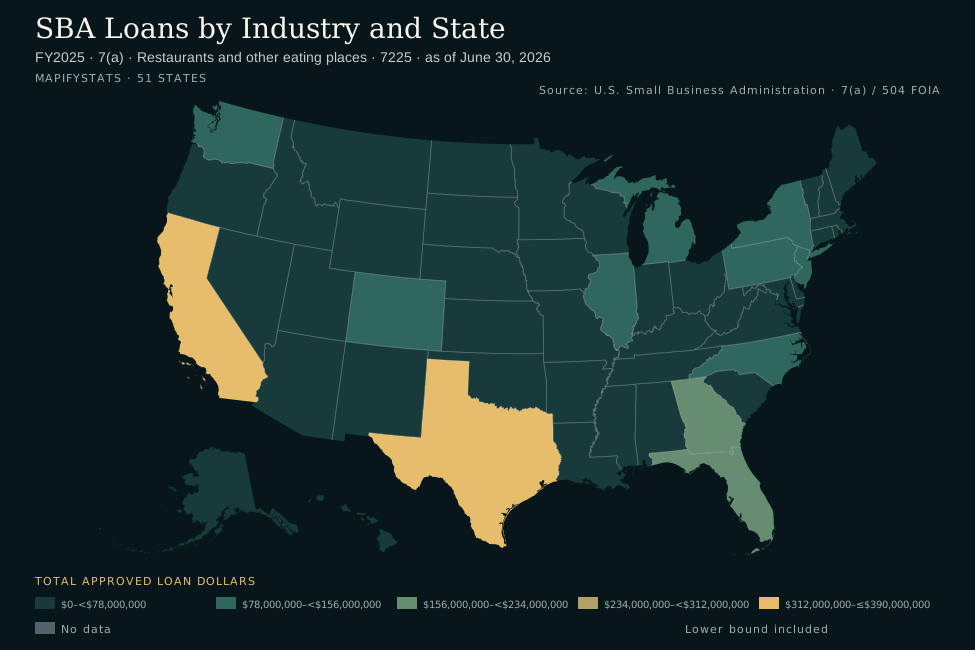
- $0–<$78,000,000
- $78,000,000–<$156,000,000
- $156,000,000–<$234,000,000
- $234,000,000–<$312,000,000
- $312,000,000–≤$390,000,000
- No data
- Lower bound included
State estimates and source notes are available below. Enable JavaScript for interactive comparisons.
Compare two states
Historical comparison
Scroll the chart horizontally to see the full period →
View chart values as a table
All 50 states and DC
Texas has the highest selected point estimate ($384,902,800); Vermont has the lowest ($1,038,500).
FY2025 · 7(a) · Restaurants and other eating places · 7225 · as of June 30, 2026
Scroll horizontally to see every column →
| Alabama | $34,835,400 | 60 loans | $350,000 | 25 |
|---|---|---|---|---|
| Alaska | $6,248,700 | 8 loans | Unavailable | 45 |
| Arizona | $69,346,200 | 117 loans | $430,800 | 14 |
| Arkansas | $8,800,600 | 28 loans | $235,800 | 41 |
| California | $384,417,600 | 780 loans | $300,000 | 2 |
| Colorado | $81,103,400 | 167 loans | $305,000 | 12 |
| Connecticut | $23,319,500 | 62 loans | $215,950 | 31 |
| Delaware | $12,173,100 | 21 loans | $320,000 | 37 |
| District of Columbia | $11,912,100 | 25 loans | $200,000 | Unranked |
| Florida | $222,667,900 | 392 loans | $411,000 | 3 |
| Georgia | $167,965,400 | 257 loans | $494,300 | 4 |
| Hawaii | $4,742,000 | 26 loans | $75,000 | 46 |
| Idaho | $21,693,400 | 50 loans | $250,900 | 32 |
| Illinois | $127,877,400 | 245 loans | $256,000 | 6 |
| Indiana | $38,929,000 | 89 loans | $250,000 | 23 |
| Iowa | $13,933,900 | 31 loans | $200,000 | 35 |
| Kansas | $25,599,100 | 46 loans | $404,250 | 29 |
| Kentucky | $24,024,500 | 45 loans | $250,000 | 30 |
| Louisiana | $34,615,000 | 54 loans | $490,700 | 26 |
| Maine | $8,093,300 | 32 loans | $214,000 | 43 |
| Maryland | $44,718,900 | 114 loans | $216,500 | 21 |
| Massachusetts | $56,734,300 | 187 loans | $150,000 | 16 |
| Michigan | $96,093,600 | 212 loans | $258,450 | 10 |
| Minnesota | $39,060,200 | 101 loans | $200,000 | 22 |
| Mississippi | $10,048,600 | 25 loans | $150,000 | 40 |
| Missouri | $55,358,600 | 90 loans | $448,500 | 18 |
| Montana | $12,966,200 | 23 loans | $330,000 | 36 |
| Nebraska | $10,382,700 | 25 loans | $140,000 | 39 |
| Nevada | $35,323,400 | 83 loans | $300,000 | 24 |
| New Hampshire | $15,820,200 | 46 loans | $118,000 | 34 |
| New Jersey | $114,362,400 | 206 loans | $272,500 | 8 |
| New Mexico | $8,464,900 | 20 loans | $190,000 | 42 |
| New York | $128,728,500 | 380 loans | $150,000 | 5 |
| North Carolina | $124,909,600 | 169 loans | $480,000 | 7 |
| North Dakota | $2,420,100 | 10 loans | $116,000 | 49 |
| Ohio | $75,764,600 | 235 loans | $150,000 | 13 |
| Oklahoma | $20,473,500 | 35 loans | $430,000 | 33 |
| Oregon | $29,225,100 | 81 loans | $150,000 | 28 |
| Pennsylvania | $95,359,100 | 215 loans | $250,000 | 11 |
| Rhode Island | $10,763,400 | 35 loans | $150,000 | 38 |
| South Carolina | $56,218,600 | 83 loans | $499,500 | 17 |
| South Dakota | $7,631,700 | 17 loans | $333,000 | 44 |
| Tennessee | $53,817,900 | 86 loans | $420,600 | 20 |
| Texas | $384,902,800 | 535 loans | $484,000 | 1 |
| Utah | $32,369,800 | 74 loans | $250,000 | 27 |
| Vermont | $1,038,500 | 12 loans | $50,000 | 50 |
| Virginia | $69,283,500 | 117 loans | $425,000 | 15 |
| Washington | $103,663,200 | 221 loans | $296,000 | 9 |
| West Virginia | $3,545,700 | 13 loans | $105,000 | 48 |
| Wisconsin | $55,198,900 | 105 loans | $318,700 | 19 |
| Wyoming | $4,046,700 | 10 loans | $94,750 | 47 |
Download every source observation as CSV ↓ · Explorer data (JSON)
Five industries, with defined NAICS coverage
Restaurants and other eating places use NAICS 7225; plumbing, heating and air-conditioning contractors use 238220; offices of dentists use 621210; child day care services use 624410; and automotive repair and maintenance use 8111. The contractor category includes plumbing and cannot isolate HVAC-only businesses. These are five selected industries, not every SBA-supported business. The program control keeps 7(a) and 504 observations separate.
Approved amounts and fiscal years
Counts and dollars aggregate non-cancelled SBA approvals by ProjectState, ApprovalFY, NaicsCode and program. GrossApproval is the total approved loan amount, not just the SBA-guaranteed portion. Fiscal years run October 1 through September 30. The June 30, 2026 source supports complete approval years FY2020–2025; partial FY2026 is excluded. Current loan status is evaluated as of the source date, so a later refresh can revise older cohorts.
Counts are not approval probabilities
The files describe approved loans, including undisbursed commitments and loans later paid off or charged off. They do not supply every rejected application, so this explorer cannot calculate an application approval rate, predict eligibility or estimate a business failure rate. A loan approval is also not proof that the full amount was disbursed. Counts are loans, not unique borrowers or unique businesses.
Zero, small samples and reproducibility
Cancelled loans and rows outside the 50 states/DC or missing ProjectState are excluded. Zero counts mean no qualifying approval records in the selected snapshot, not no demand or no lenders. Counts and dollar totals retain small cells; median loan amounts require at least ten qualifying loans. Smaller medians remain unavailable instead of displaying an unstable benchmark. A compact source extract retains only the six analytical fields needed to reproduce the aggregates, with the original download checksum. No borrower or lender directory is published.
Source and reproducibility
U.S. Small Business Administration · 7(a) / 504 FOIA. Sources retrieved October 1, 2026. The snapshot stays fixed until a reviewed data refresh; this page does not claim live data.
Archived source files, selection rules and SHA-256 checksums.
Common questions
Can this tell me whether my restaurant will receive a loan?
No. It shows observed approved amounts, not application outcomes for all applicants.
Why can a state have loan dollars but no median?
The count is fewer than ten. The amount is retained, while the median benchmark is withheld by this explorer’s minimum-count rule.